
When a private equity firm buys a business, the headline number is the enterprise value. What actually gets negotiated (and rarely gets a plain-language walkthrough of) is how much of that price is being financed with borrowed money, and where that money sits once the deal closes. The debt is not the buyer’s problem to service after closing. It becomes the company’s problem: the same company where a founder may be holding rollover equity, waiting on a seller note, or simply watching from the sidelines as a business they built absorbs a capital structure they did not design.
Leverage is not incidental to how private equity generates returns. It is one of three structural levers sponsors use to turn a business’s operating performance into an outsized return on their own invested capital, and it is the one lever that works exactly the same way in reverse. The same mechanics that amplify gains when a deal goes well can equally amplify the losses when it doesn’t.
This matters immediately to any founder negotiating a deal structure. Falcon’s Deal Structure Playbook covered the four building blocks of what a founder may receive: cash at close, rollover equity, a seller note, and an earnout. This report goes one level deeper, into the mechanism sitting underneath all four: the debt the buyer raises, how it drives the sponsor’s return math, and the specific terms a founder can and should negotiate before that debt becomes a live risk to money they have not yet collected.
Private credit, not banks, now finances the large majority of lower-middle-market buyouts, and the market has grown fast enough to change how deals get structured. Direct lending alone has reached roughly $1.5 to $2 trillion in assets, on pace to approach $3 trillion by 2028, and the broader private credit market, including mezzanine and asset-based strategies, is estimated near $2 trillion with $450 to $550 billion in uncommitted capital still waiting to be deployed.
That capital is not chasing deals on the same terms it did a few years ago. After a period of looser, more borrower-friendly lending, 2026 has brought what several credit market observers describe as a “lender-friendly reset”. New loans increasingly carry less leverage, more financial covenants, fewer payment-in-kind interest arrangements, and tighter documentation than deals signed two or three years earlier. For a founder negotiating today, that shift is in their favor. Lenders are asking harder questions about leverage and covenant protection than they were in 2021 and 2022, which is leverage a founder can use in their own negotiation, if they understand what the lender is already pushing for.
Leverage in the lower middle market has also settled at meaningfully more conservative levels than the market’s last peak. Multiple independent data sources place total debt for lower-middle-market buyouts in the 3x to 5x EBITDA range, with GF Data’s broad $10 million to $500 million transaction universe averaging 3.6x total debt in 2025, down from a 4.0x peak in 2021. Upper-middle-market deals, by contrast, typically carry 5.0x to 5.5x. This is directionally reassuring for founders selling into this segment, but it is an average, not a ceiling, and private credit lenders have shown they will stretch beyond bank limits, sometimes to 5.0x or higher, for the right borrower.
Before any of the mechanics below matter, it helps to understand what each party wants from the capital structure, because none of them are optimizing for the same thing a founder is.
Private equity sponsors is trying to maximize a fund-level return measured two ways: MOIC (multiple of invested capital), and IRR (annualized rate of return). IRR is highly sensitive to timing; a 2.5x return realized in three years produces roughly 36% IRR, while the same 2.5x stretched over five years produces roughly 20%. That timing sensitivity is why sponsors have a structural incentive to extract cash from a portfolio company as early as possible, through fast deleveraging, add-on acquisitions, or a dividend recapitalization, rather than waiting patiently for a single exit years later.
The lender, whether a bank or private credit fund is trying to get its principal and interest back on schedule, and is largely indifferent to how well the equity holders do beyond that. Lenders protect that outcome primarily through covenants: contractual promises embedded in the credit agreement that give the lender an early warning, or an outright veto, before the company can take actions that increase the lender’s risk.
A founder holding rollover equity or a seller note, sits underneath both of these parties in the capital structure, and above them in one respect that matters: unlike the sponsor and the lender, a founder is negotiating the terms that govern this relationship once, at the moment of sale, and largely has to live with what gets written into the documents at closing.
Private equity returns decompose cleanly into three components, and understanding the split is the foundation for everything else in this report. Analysts call this returns attribution: taking the total equity value created in a deal and breaking it into the specific mechanism that produced it.
Lever | Typical Share of Returns | Who Controls It |
|---|---|---|
EBITDA growth | 40% – 60% | Largely the sponsor, through the operating plan |
Debt paydown (deleveraging) | 20% – 30% | Partly the sponsor, mostly the company’s free cash flow |
Multiple expansion | 10% – 30% | Mostly market conditions at exit, outside anyone’s control |
EBITDA growth is the lever institutional investors trust most, because it reflects real operating improvement and is the only one substantially inside the sponsor’s control. Multiple expansion is the least reliable, since it depends on market appetite at exit, which is why disciplined underwriting assumes no multiple expansion in a base case at all. Debt paydown sits in between: it is mechanical and predictable once the deal is financed, but it only works as designed if the company generates enough free cash flow to service and reduce the debt on schedule. When that cash flow falls short, because revenue softens, costs rise, or the initial leverage was simply too aggressive, the same mechanism that was supposed to build equity value instead starts eroding it.
The first three items below explain how leverage drives a sponsor’s return. The last three are the specific terms a founder can negotiate to control how much risk lands on money they don’t receive up front
Plain-language definition. The increase in the company’s operating profit over the hold period, through revenue growth, margin improvement, or both. Every dollar of EBITDA growth is worth the entry multiple in added enterprise value; at a 10x multiple, $1 of new EBITDA creates $10 of enterprise value.
Why it matters to a founder. This is the lever sponsors point to when they pitch a deal as a partnership rather than a financial engineering exercise, and it is usually genuine. Bain & Co’s 2024 Global Private Equity Report found operational improvement, not leverage or market timing, contributed the majority of PE returns across the 2018 to 2023 funds. However, a founder holding rollover equity is exposed to the downside as directly as its upside. If the operating plan underperforms, the equity value the founder rolled into is the first cushion absorbing that miss, not the debt.
Founder Action. Ask what specific initiatives the sponsor’s operating plan assumes, and over what timeline. A plan built on realistic, itemized initiatives (e.g. consolidating locations or repricing contracts at renewal) is a different risk profile than one built on an assumed margin expansion with no stated mechanism behind it.
Plain-language definition. As the company uses free cash flow to pay down acquisition debt, the equity slice of the capital structure grows, because enterprise value minus a shrinking debt balance leaves more for equity holders. Many credit agreements include a cash sweep provision that automatically directs 50% to 75% of excess cash flow toward mandatory debt repayment, accelerating this process.
Why it matters to a founder. This is the most predictable of the three return levers in a healthy scenario, and the most dangerous in a stressed one. Leverage mechanically amplifies both directions: moving entry leverage from 5x to 6x EBITDA on an otherwise identical deal increases projected MOIC and IRR, because the same dollar of enterprise value gain now sits on a smaller equity base. But it also means a smaller EBITDA shortfall consumes a proportionally larger share of that equity cushion, and slower-than-planned debt paydown directly increases the odds of a covenant breach.
Founder Action. Ask what leverage multiple the buyer is financing the deal at, relative to the 3x to 5x range typical for this segment, and what the base-case deleveraging schedule assumes for free cash flow. A deal financed at the aggressive end of that range, or above it, is a company that will have less room to absorb a slow quarter.
Plain-language definition. The gain created when a company is sold at a higher EV/EBITDA multiple than it was purchased at. If a sponsor buys at 9x and exits at 11x, that two-turn expansion applies to the entire exit-year EBITDA, not just the growth achieved during the hold.
Why acquirers care. Multiple expansion is real when it happens, usually because the business genuinely improved (e.g. better recurring revenue mix, reduced customer concentration, a larger, more diversified platform after add-on acquisitions) or because multiples in the broader market increased. But disciplined underwriting treats it as upside, not a base-case assumption, precisely because it is the one lever no one in the deal controls (depends on another buyer in a future market). A sponsor whose return math depends on multiple expansion to work is more likely to lean on the other two levers, growth and leverage, harder than a sponsor underwriting a flat exit multiple.
Founder Action. If a buyer’s story for the deal leans heavily on paying a premium multiple today because the exit will command an even higher one, treat that as a signal to look more closely at how much leverage is funding the gap between today’s price and today’s fundamentals.
Plain-language definition. A covenant is a contractual promise in the credit agreement that either requires the company to maintain certain financial metrics (a maintenance covenant) or restricts specific actions like taking on more debt or paying a dividend (an incurrence covenant). Simply put, maintenance covenants are tested on a regular basis, and incurrence covenants are tested only when circumstances require it. A maintenance covenant is a routine check-up. An incurrence covenant is a permission slip the company needs only when it wants to do something specific, such as borrow more or pay a dividend.
Why it matters to founders. Private credit lenders, who finance most lower-middle-market deals today, overwhelmingly retain maintenance covenants, unlike the broadly syndicated loan market, where roughly 85% of deals are now covenant-lite. That is good news for a founder with rollover equity or a seller note: a maintenance covenant creates an early, contained warning (a technical default, quarterly-tested, typically with a 30-day equity cure window before it escalates) rather than letting a struggling company run all the way to a payment default before anyone intervenes. The most common maintenance test is a maximum leverage ratio, present in ~30% of deals, with over half of deals including some combination of leverage, interest coverage, or fixed-charge coverage tests.
Founder Action. Ask what the closing leverage ratio is and what cushion the maintenance covenant allows above it before a technical default is triggered. A thin cushion (say, 5% to 10% above closing leverage) leaves far less room for a normal bad quarter than a cushion of 20% or more. If a seller note or rollover equity is part of the deal, ask whether the purchase agreement gives any notice rights if the company approaches a covenant threshold.
Plain-language definition. A seller note is a loan a founder effectively makes to the buyer for part of the purchase price, repaid over time with interest. In lower-middle-market deals, terms typically run 4% to 8% interest over three to seven years. Because the buyer’s senior lender will almost always require the seller’s note to rank behind its own debt, a subordination agreement, signed by the founder, the buyer, and the senior lender, governs exactly how far behind.
Why it matters to founders. care. Subordination is not one clause; it is a bundle of separate rights, each independently negotiable. The most consequential is the standstill period: how long a senior lender can block the founder from enforcing the note or accelerating payment after a default. Market practice runs 90 to 180 days, with senior lenders pushing for the long end and sellers pushing for the short end. A founder who accepts subordination without limiting its scope, and without a security interest in company assets, has a claim that is legally real but practically very hard to collect on if the business is already in distress.
Founder Action. Negotiate the standstill period, a security interest in identifiable assets (a recorded claim, typically a UCC-1 lien, against specific company property that can be seized if the note goes unpaid), and a right to cure (the ability to step in and fix a default on the senior debt yourself, rather than watch the lender’s remedies wipe out your note) before agreeing to any seller note, not after. These are standard, well-precedented asks in lower-middle-market deals, not unusual demands, and a buyer’s unwillingness to discuss them is itself useful information about how the rest of the negotiation will go.
Plain-language definition. Rollover equity is the portion of the purchase price a founder reinvests into the buyer’s ownership structure instead of taking as cash, typically 10% to 40% of total consideration in lower-middle-market deals. The percentage is the number every founder focuses on. The governance rights attached to that stake, largely invisible in a term sheet’s headline terms, determine whether it behaves like a real ownership interest or an illiquid number on a cap table.
Why it matters to founders. A sponsor will almost always hold “drag-along rights”: the contractual power to force a minority holder, including a founder’s rollover stake, into a future sale on the sponsor’s terms. That is standard and not alone a red flag. What matters is whether the founder has negotiated tag-along rights in return, the right to sell alongside the sponsor on the same terms rather than being left behind, along with information rights (regular financial reporting) and a board observer seat, if possible. None of these prevent the sponsor from using leverage, pursuing a dividend recapitalization, or running the business its own way. What they do is ensure the founder finds out about material decisions, including new debt raised against the business, before they show up as a surprise in a year-end distribution notice.
Found Action. Negotiate tag-along rights, information rights, and anti-dilution protection as a condition of any rollover, not as an afterthought once the rollover percentage is agreed. Ask specifically whether a future dividend recapitalization, a common way sponsors accelerate their own returns by adding new debt to pay themselves a distribution, would require the founder’s consent or even notice.
The six items above are easier to hold together with one simple comparison.
Think of it the way you would think of a mortgage. Two people buy the same $500,000 house. One puts down $200,000. The other puts down $50,000. If the house rises to $600,000, the second buyer’s equity triples while the first buyer’s grows by half. If the house falls to $400,000, the second buyer’s down payment is gone and the first buyer still has equity left. The house performed the same way in both cases. The only difference was how much was borrowed.
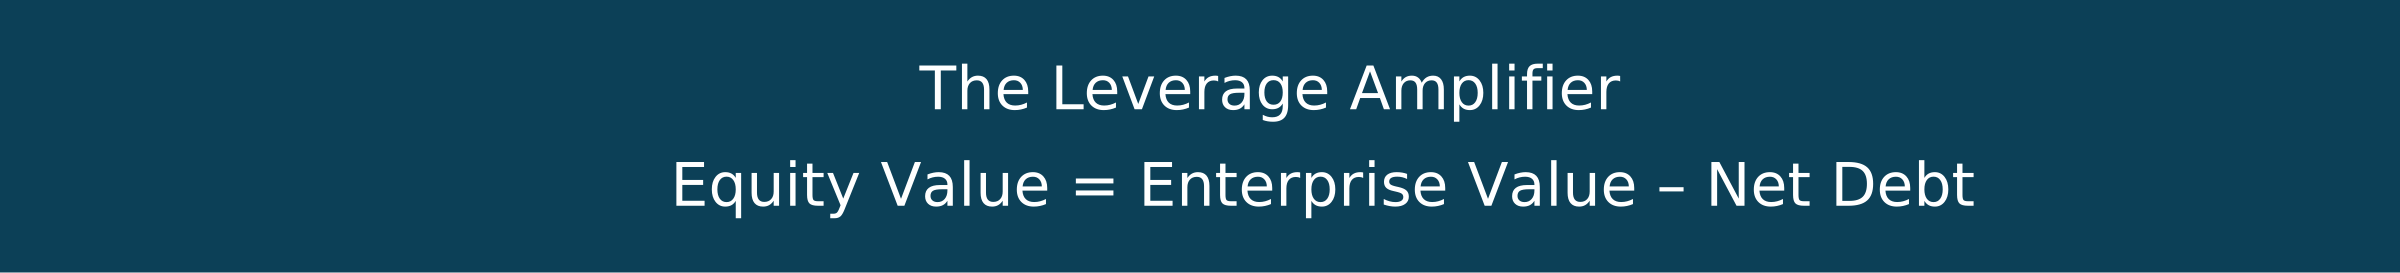
A leveraged buyout works the same way. Equity value equals enterprise value minus net debt. The more debt sits underneath a business, the bigger the effect any change in enterprise value has on the equity above it, in both directions.
Here is the same idea with simpler numbers. A buyer purchases a company for $50 million. The company earns $5 million of EBITDA, so the price is 10 times earnings.
In the first version, the buyer borrows 5x EBITDA, or $25 million, and puts in $25 million of its own equity. In the second version, the buyer borrows 6x EBITDA, or $30 million, and puts in only $20 million. Same company, same price, one more turn of debt.
Now run both forward five years. EBITDA grows to $6.5 million. The company pays down $10 million of debt. The exit multiple is unchanged at 10x, so the business sells for $65 million.
The 5x deal: $65 million less the $15 million of debt still outstanding leaves $50 million of equity, against $25 million invested. A 2.0x return.
The 6x deal: $65 million less $20 million of remaining debt leaves $45 million, against $20 million invested. A 2.25x return.
The sponsor earns the better multiple on the 6x deal even though the business created $5 million less equity value in total. The same operating result landed on a smaller equity slice.
Now run it in reverse. If EBITDA comes in at $4.25 million instead of $5 million, the whole enterprise value hit lands on a smaller equity cushion in the 6x deal than in the 5x deal. The weaker cash flow also slows debt paydown, tightening covenant headroom at the exact moment the company can least afford a technical default. This is the mechanism, not a hypothetical risk: the same capital structure that amplifies gains when a deal performs amplifies losses when it doesn’t, and a founder’s rollover equity and seller note sit inside that structure either way.
Two founders can sign deals with identical headline enterprise values and identical rollover percentages, and end up with very different outcomes, entirely because of how the underlying leverage and negotiated protections differ.
The following is a labeled illustrative scenario constructed to demonstrate the mechanics, not a record of an actual transaction.
Two founders, at Company A and Company B, each sell a business for a $30 million enterprise value. Each takes $21 million in cash at closing, rolls $6 million (20% of the price) into equity in the buyer’s new company, and accepts a $3 million seller note for the rest. On paper the two deals look identical. The $9 million neither founder has collected yet is where they diverge.
Company A (Negotiated Protections) | Company B (Standard Terms) | |
|---|---|---|
Entry leverage | 3.5x EBITDA (within typical LMM range) | 5.5x EBITDA (aggressive for this segment) |
Covenant structure | Maintenance covenant, 20% cushion above closing leverage | Incurrence-only; no routine testing |
Seller note | 90-day standstill, secured, right to cure | 180-day standstill, unsecured |
Rollover equity rights | Tag-along, information rights, board observer | Drag-along only; no information rights |
Dividend recap consent | Founder notice and consent required | No consent or notice rights |
Outcome if EBITDA misses plan by 15% | Covenant cushion absorbs the miss; founder is notified | Covenant breach likely; founder learns from a lender communication, if at all |
Both founders have $9 million riding on what happens after closing. Company A’s founder negotiated a capital structure and a set of contractual rights that turn a bad quarter into a manageable, visible event. Company B’s founder faces the same bad quarter as a likely covenant breach, learned about after the fact, with a seller note that is hard to collect and rollover equity that carries no right to be told what happened.
1. What leverage multiple is the buyer financing this deal at?
Compare it to the 3x to 5x EBITDA range typical for lower-middle-market deals. Anything meaningfully above that range means less cushion if performance softens.
2. Does the credit agreement include maintenance covenants, and what is the cushion above closing leverage?
Compare it to the 3x to 5x EBITDA range typical for lower-middle-market deals. Anything meaningfully above that range means less cushion if performance softens.
3. What does the seller note’s subordination agreement say about the standstill period, security, and the right to cure?Compare it to the 3x to 5x EBITDA range typical for lower-middle-market deals. Anything meaningfully above that range means less cushion if performance softens.
4. Does the rollover equity come with tag-along rights, information rights, or a board observer seat?
A sponsor will hold drag-along rights by default. Tag-along and information rights are the founder’s side of that same bargain, and are rarely offered unless asked for.
5. Would a future dividend recapitalization require my consent or notice?
Dividend recaps add debt to a company specifically to pay the sponsor a distribution. Without a consent or notice right, a founder with rollover equity can watch this happen with no say in it.
6. What does the sponsor’s operating plan assume for EBITDA growth, and how much of the return math depends on multiple expansion?
Compare it to the 3x to 5x EBITDA range typical for lower-middle-market deals. Anything meaningfully above that range means less cushion if performance softens.
The leverage terms, covenant structure, and governance rights covered in this report are not decisions a founder revisits after closing. They are negotiated once, in the weeks before signing, and they are far easier to negotiate before a buyer has a signed agreement than after. Three of the six items above are effectively fixed at closing and cannot be renegotiated later without the other side’s agreement:
Two items can, in practice, still be raised after closing, though from a much weaker negotiating position: covenant amendments (lenders will renegotiate a struggling credit, usually for a fee and a rate increase) and consent rights around a specific transaction like a dividend recap, if the governing documents left room for that discussion at all.
The founders who end up protected are rarely the ones who negotiated hardest on the headline multiple. They are the ones who asked what was financing that multiple, and who made the leverage, the covenants, and their own governance rights part of the negotiation before there was a signature on the page.
There is no single, universally applied standard governing leverage multiples, covenant structure, or seller note and rollover terms across lower-middle-market transactions. The ranges above are drawn from 2025 and 2026 market data, private credit industry research, and legal and advisory commentary on deal terms, not a uniform or audited industry benchmark. Individual lenders and sponsors set terms based on deal size, sector, credit quality, and competitive dynamics at the time of the transaction. Where sources presented different figures, this report presents the range rather than averaging it into a false precision. Use these benchmarks to inform a negotiation, not to predict the specific terms any one buyer will offer.
Falcon offers a Deal Structure Risk Review for founders in a live or upcoming process: a confidential read of the leverage, covenants, and negotiation terms in your specific deal, and what to push back on before you sign. To learn more, contact Don Wanner (dwanner@falconllc.com) or Julian DeOliveira (jdeoliveira@falconllc.com).
© 2026 Falcon Capital Partners. All rights reserved. This article is intended for informational purposes only and does not constitute investment, legal, or financial advice.